Germany’s VAT holiday worked—if you saw it. Durables up 37%, total spending up 4.4%
When the government makes today’s purchases a little cheaper than tomorrow’s, do people actually bring spending forward—and which households jump first? That was the core question behind a new analysis of Germany’s temporary value‑added tax (VAT) cut during the pandemic.
The study, published in the Review of Economic Studies, asks whether a short, clearly time‑limited tax cut can work like a shot of monetary policy by nudging shoppers to act now rather than later, and who benefits when it does.
What changed at the checkout
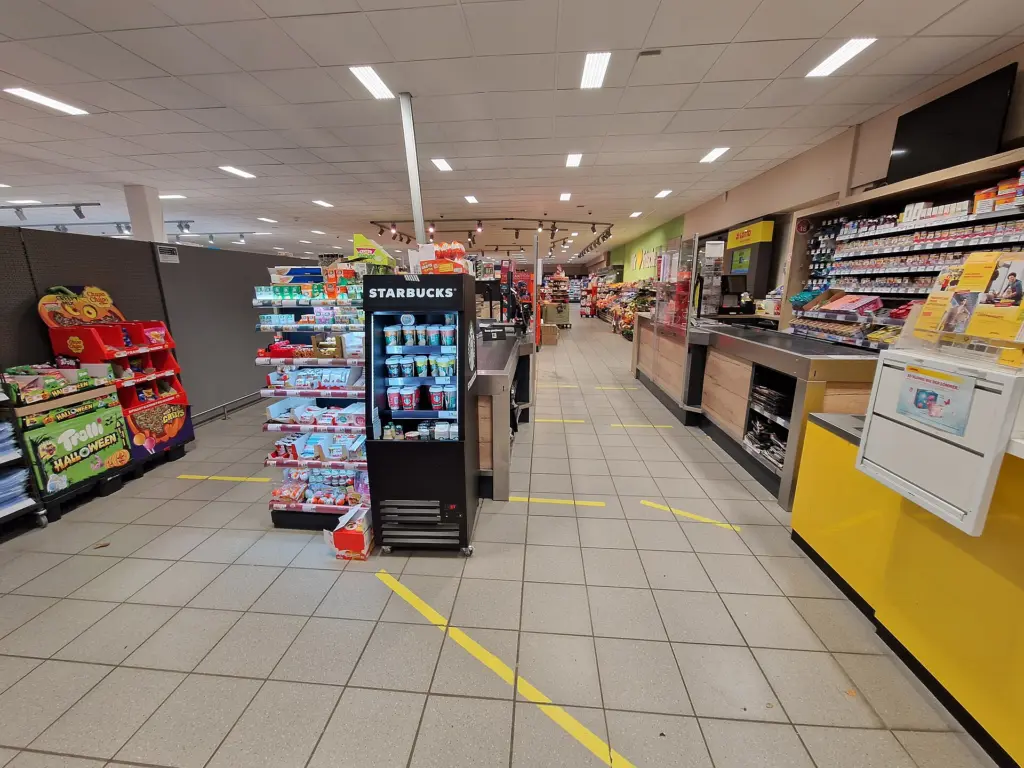
Germany lowered VAT from 19% to 16% for half a year. The simple arithmetic: if prices fall now and are set to rise again on a known date, waiting gets more expensive in real terms. That is the intertemporal nudge this study set out to measure and model.
Crucially, the analysis distinguishes between households that actually perceived the tax cut showing up in prices and those that did not. That perception gap turns out to map onto very different spending behavior.
How they measured behavior, not just opinions
The researchers paired survey evidence with behavioral outcomes and a macro model. In a July 2020 survey, households who knew the VAT cut was temporary were more likely to plan big‑ticket purchases than those who did not—a gap of about 10 percentage points. That expectation channel is the setup for what follows.
On actual spending, the study compares households by how strongly they believed stores passed the tax cut through to prices. Those who saw a strong pass‑through spent around 37% more on durable goods than households who perceived little or none. For medium‑durability goods, such as books, the bump was around 10%.
What the model says about the whole economy
Zooming out from categories to the macro level, the researchers’ model estimates that the VAT cut drove up total consumption spending by 4.4% immediately after it started. In plain English: against the baseline where no cut happens, the model’s average household steps up spending by roughly one in twenty‑three euros right away.
The response wasn’t uniform. The strongest reactions came from younger and middle‑aged households with lower net wealth. The study also reports that the price incentive reached households that conventional stimulus programs often struggle to move.
Who benefited most—and why that matters
Lower‑wealth households, and younger and middle‑aged households in particular, benefited most. That pattern matters because it suggests the policy didn’t only accelerate purchases that affluent households would have made anyway—it also shifted behavior in groups that typically have tighter budgets.
The authors further argue that a temporary VAT cut can be particularly effective when interest‑rate policy is up against its limits, such as when key rates are near zero. In that scenario, making today’s sticker prices predictably lower than next year’s can substitute, to a degree, for a rate cut that’s no longer available.
What the numbers look like at a glance
| Measure | Estimated effect |
|---|---|
| VAT rate change | 19% to 16% for half a year |
| Durable goods spending (among households perceiving strong pass‑through) | +37% vs. households perceiving little/no pass‑through |
| Medium‑durability goods (e.g., books) | +10% |
| Plans for major purchases in July 2020 survey | +10 percentage points if households knew the cut was temporary |
| Total consumption (model, immediately after start) | +4.4% |
| Groups with strongest response | Younger/middle‑aged, lower net wealth |
Limits: what this study does and doesn’t claim
The authors explicitly note that their findings do not speak to the fundamental merits of the 2020 VAT cut itself—only to how a temporary VAT change can affect spending behavior and who responds. That is an important boundary line: the paper estimates behavioral and macro responses, not the full welfare accounting of the policy.
Any such conclusions also rest on two moving parts that are hard to pin down in real time: how much of the tax cut retailers pass through to prices, and how clearly households understand the cut is temporary. If either channel were weaker than assumed or measured, the effects would shrink accordingly.
The deeper cut
Intertemporal substitution, in practice
In textbook terms, a temporary VAT cut raises the relative price of future consumption versus current consumption: Pt+1/(1+τt+1) versus Pt/(1+τt). If τt < τt+1 for a known interval, the Euler equation implies higher current consumption for goods where timing is flexible and adjustment costs are modest. The empirical 37% for durables fits that logic: durables have high elasticity to anticipated price paths because (i) purchases are infrequent, and (ii) utility flows over many periods once installed. Medium‑durability items, like books, show a smaller but still material elasticity (~10%), consistent with lower lumpy‑purchase margins and smaller absolute discounts. The 4.4% aggregate model response is the general‑equilibrium counterpart: not every euro moves—the least deferrable categories barely budge—but enough durable and semi‑durable demand shifts forward to lift the consumption aggregate. Heterogeneity matters: lower‑wealth, younger cohorts face tighter liquidity and steeper marginal propensity to consume. When a VAT cut is immediately salient at the till, it relaxes effective liquidity by lowering current prices without requiring credit access. That salience also sidesteps the interest‑rate transmission’s weak spots—no need to refinance or notice a basis‑point tweak when the price tag itself changes.
If rates hit zero, what then?
One policy takeaway the authors float is conditional: when the central bank’s interest‑rate policy is at its limits, a temporary VAT cut can be a particularly effective tool. That is because it directly boosts disposable income and creates a predictable incentive to move purchases forward, especially for households that traditional stimulus doesn’t easily reach.
One unknown, answered once
You might ask whether the policy was “worth it” overall—did the benefits beat the costs? The study doesn’t answer that. Its authors draw a bright line: these results document who spent more, by how much, and when, not the broader cost‑benefit merits of that particular tax cut.
The paper: A Temporary VAT Cut as Unconventional Fiscal Policy (Review of Economic Studies, 2026)
Sources: New study shows COVID value-added tax cut significantly boosted private consumption (phys.org)
Images: Cover: Everyman Science (illustration); Figure 1: Borislava3638 / Wikimedia Commons
How this article was made: Everyman Science uses AI tools to structure, format and optimise its articles, and occasionally to produce illustrations where no free photograph exists. The reporting these articles are based on is human-produced and cited above. Spotted an error? Write to [email protected] and we will correct it. — The editors How we work.




Science desk team of Everyman Science, curating and reporting on the day’s most significant developments in research, space exploration, and technology.